Stocks and bonds are losing ground in early trading, with gold and silver falling alongside. Crude oil prices are up a bit along with the dollar.
We just got a fresh look at inflation – and it wasn’t great. The Consumer Price Index rose 0.6% in September, the most since April. Plus, the core CPI that excludes food and energy rose a greater-than-expected 0.3%. The Federal Reserve has two more meetings scheduled for 2026 – one concluding on Oct. 28 and the other on Dec. 9. The hot CPI data modestly boosted the chances of a hike later this month.
Meanwhile, another data center company just delayed its Initial Public Offering (IPO) – and AI stock investors are taking notice. The Australian company AirTrunk punted on plans to raise $1 billion-plus in Singapore, delaying the offering until 2027. That followed the postponement of a $5 billion offering by Firmus Grid in Australia. It would’ve been the largest IPO in that market in decades.
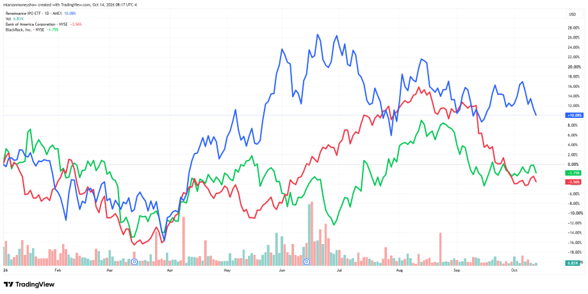
IPO (Blue), BAC (Red), BLK (Green) - YTD % Change
Source: TradingView
What’s the problem? Investors are reconsidering the lofty valuations previously assigned to data center developers and operators. Questions are also being raised about demand for their compute services, higher financing and development costs, and political pushback in several jurisdictions. Semiconductor stocks, for their part, got hammered earlier this week amid worries about cheaper Chinese competition in the memory chip business. Still, the Renaissance IPO ETF (IPO) is up 10% year-to-date.
The big bank earnings parade is rolling on, with Bank of America Corp. (BAC) the latest to report third-quarter results. They were underwhelming, with adjusted profit of $1.08 per share and revenue of $30 billion both missing analyst forecasts. BofA stock slipped 3% after entering the session down 3.5% YTD.
On the flip side, asset management giant BlackRock Inc. (BLK) reported better-than-expected adjusted EPS of $15.93 and sales of $7.7 billion. Its shares popped 4% in response. They were down 1.7% YTD as of yesterday’s close.