Elections have consequences. And the magnitude of Democrats’ 2026 gains stacks up with other historic change elections, including 1974 and 1994. One company likely to benefit disproportionately is Brookfield Renewable Partners LP (BEP), writes Roger Conrad, editor of Conrad’s Utility Investor.
Democrats will hold as many as 56 Senate and 260 House seats in the US Congress that takes control in January. More important for utilities, the party flipped control of at least five governorships and 12 state legislative chambers.
Brookfield Renewable Partners LP (BEP)
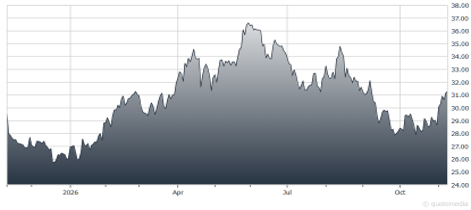
BEP should benefit. The contract power producer is coming off an extremely strong Q3, with funds from operations per unit rising 10.9% on a 43.9% lift in utility scale solar cash flow. That prompted management to raise 2026 guidance to “in line or ahead of our long-term targets,” which include 10% annual growth in FFO per share.
Business growth is also accelerating. The company brought 5.6 GW of new renewable energy online in the first nine months of the year, staying on track to reach a 10 GW annual pace in 2027. It won 1.6 GW of new long-term contracts during the quarter and successfully re-contracted a portion of its hydro fleet at attractive prices. And it financed a meaningful portion of growth with $2.8 billion sales of “noncore” assets.
The company is still rounding up votes from BEP unitholders to consolidate partnership units with BEPC shares into a single C-Corp NYSE listing. That looks like only a matter of time, with BEPC approving and more than 99% of BEP voting to date agreeing to terms on the entirely tax-deferred transaction. Winning approval will provide a boost for the combined stock.
Recommended Action: Buy BEP.