Albemarle Corp. (ALB) is the newest addition to the portfolio. We’ve watched the name since 2019 and have been waiting for the right valuations, financial conditions, and outlook to emerge. In the past few months, the stars aligned to yield all three at once, notes Philip MacKeller, editor of Contra the Heard.
This lithium and bromine chemical company is volatile because its business prospects shift sharply based on the price of lithium. This volatility acts as a double-edged sword. When prices go up, ALB roars, and when they soften, the stock plummets.
Albemarle Corp. (ALB)
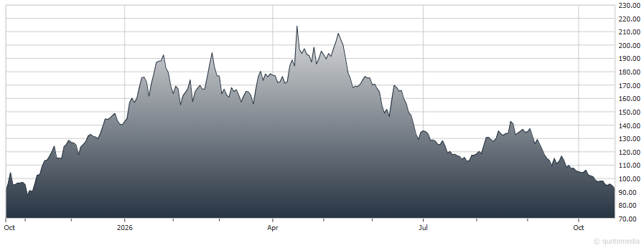
This would be concerning if Albemarle’s balance sheet was in bad shape, but such is not the case. Over the past 18 months, the executive team has executed a masterful turnaround that has cut costs, slashed capex, simplified the organization, and reduced leverage.
Since the end of 2024, the margin profile has improved, quarterly capex has contracted from $342.8 million to $71.7 million, and net debt to adjusted EBITDA has decreased from 3.5 times to 0.5 times.
In addition to the turnaround, the outlook for the remainder of 2026 is positive. The C-suite expects capex to remain tight, minimal disruption to lithium sales volumes related to a June fire at a plant in Australia, and higher net sales and adjusted EBITDA from its Specialties division.
Recommended Action: Buy ALB.