Investors are understandably nervous as October winds down. Geopolitical headlines, a sharp selloff in AI and technology stocks, and a jump in volatility have soured the market’s mood fast. But as of last Thursday’s close, the S&P 500 Index (^SPX) was just 2% below its all-time high, observes Jeff Hirsch, editor-in-chief of The Stock Trader’s Almanac.
The Nasdaq shed 2.6% last Thursday – its worst day since June 5. But the mood has deteriorated much faster than the fundamentals or the technical condition of the market.
(Editor’s Note: Jeff will be speaking at the 2026 MoneyShow Masters Symposium Sarasota, scheduled for Nov. 30 – Dec. 2. Click HERE to register.)
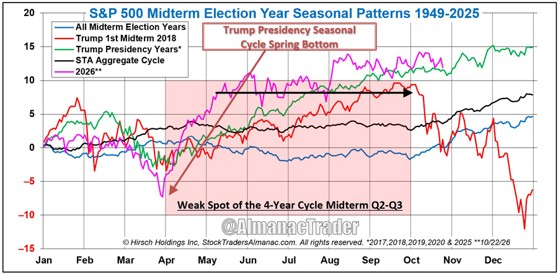
What we are witnessing looks like a classic late-October “Octoberphobia” event, and it is arriving just as several of the most bullish seasonal forces of the four-year cycle are about to converge. Volatility could persist. But the evidence still points to a post-midterm election rally, not a major market breakdown.
While the Nasdaq has taken the brunt of the selling, it was recently only 5.8% off its Oct. 6 high of 27599.79. The Dow was also back above its 50-day moving average and well above its September low. That is not what a market failure looks like.
Several defensive and cyclical sectors continue to advance. The weakness is concentrated in one corner of the market: AI, semiconductors, and high-growth leadership stocks. Markets are reacting to headlines and uncertainty, not to widespread technical deterioration.
In other words, leadership is rotating, not disappearing. Healthcare is hitting or approaching all-time highs. Consumer staples are outperforming. Real estate is improving. Materials are holding up. Transports are positive. Money is moving to other areas, not leaving.