Let me lead with the contradiction that defines recent trading action: Front-month Brent crude is up 76% year-to-date, while WTI is up 77%. The global interest rate complex has repriced higher as though that was fueled by a demand boom. It is not, advises Michael Gayed, editor of The Lead-Lag Report.
The move traces to supply destruction: US strikes destroyed three Iranian crude tankers near Kharg Island on Sept. 5 and five more in the Gulf of Oman on Sept. 8 in retaliation for ballistic missile attacks on US warships. Meanwhile, the Strategic Petroleum Reserve (SPR) has been drawn down to roughly 286.6 million barrels, its lowest level since 1982.
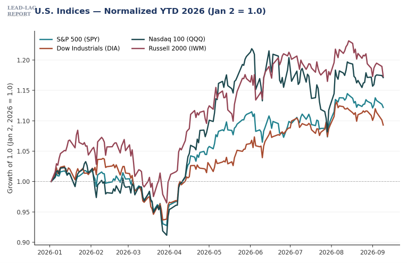
Copper — the one cyclical that cannot fake a growth signal — fell just 0.8% on the week and sits up 16.2% for the year...flat for a third consecutive week. In my view, the market is missing the distinction that matters most: Policymakers are about to tighten into a shock the commodity complex has spent three weeks refusing to call growth.
I’ll be watching this week whether the Federal Reserve actually hikes into the supply shock, and what the statement and dot plot say about oil. Tightening that treats a chokepoint as an output gap is the policy error I’m warning about.
Stock traders should also keep an eye on the long end of the yield curve. The 30-year at 5.25%, gilts at 5.37%, and JGBs at 3% are the same trade in three currencies. The global term premium is where the real policy transmission happens.