Aerospace and defense design and manufacturing is one of the core competencies of the US economy, along with allocating capital, developing medicines, and designing innovative technology. Lockheed Martin Corp. (LMT) is one of our top ideas in the sector, notes John Eade, president of Argus Research.
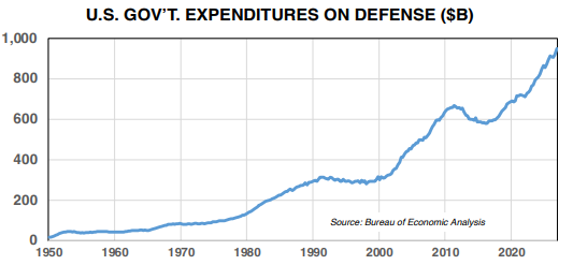
In our view, the sector is positioned for solid growth over the next few years. In 2027, US spending for national defense is expected to grow by 6% from 2026 and approach $1 trillion. Looking further ahead, industry forecasts call for domestic defense spending to grow at a CAGR of 5.8% and top $1.1 trillion by 2028.
Meanwhile, the recovering global airline industry also bodes well for commercial aerospace demand over the next several years. Airline passenger levels and airline revenues are once again growing at a healthy pace.
Lockheed has delivered consistent positive surprises to Wall Street in recent years, regardless of whether defense spending is rising or falling, or if a Republican or a Democrat occupies the White House. We have a favorable view of the company’s focus on international revenue diversification (now more than 25% of sales) and expect ongoing geopolitical tensions to benefit sales and earnings.
New management has signaled that near-term earnings growth will slow, though the long-term outlook remains upbeat. Meanwhile, the company remains committed to shareholder returns via an aggressive share-repurchase program and regular dividend hikes. The current yield is 2.6%.
Recommended Action: Buy LMT.