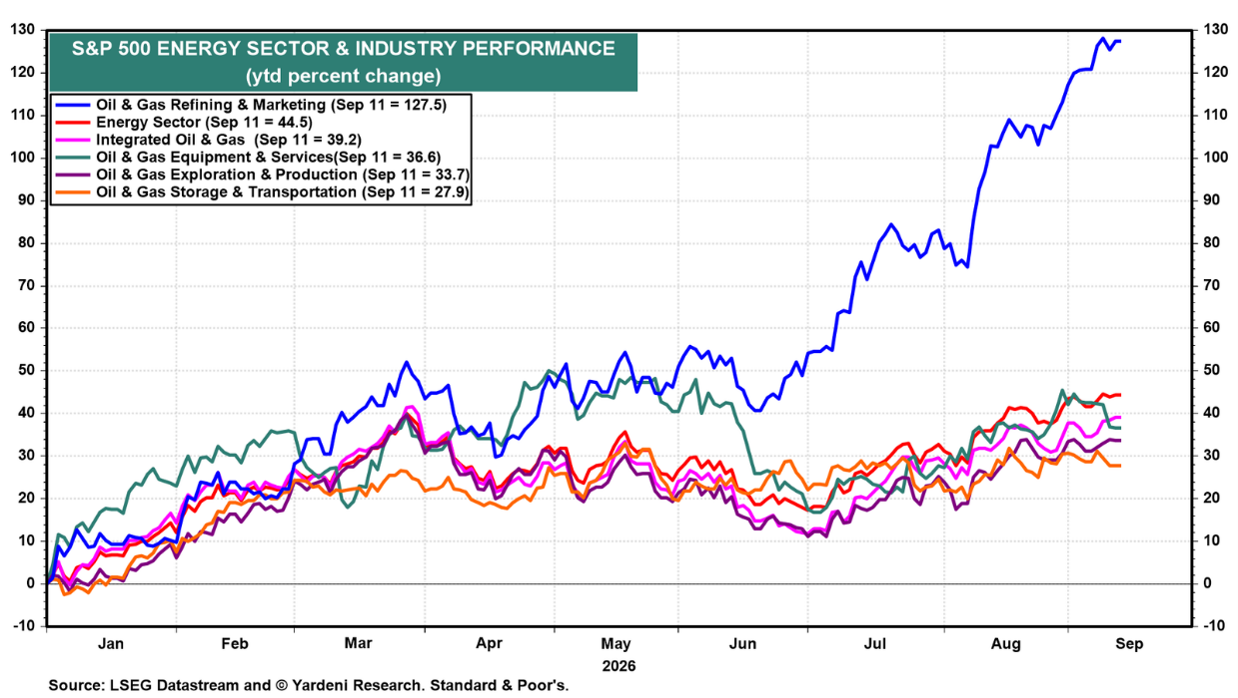
Rising bond yields and oil prices weighed on stocks last week, though a mostly in-line CPI report on Friday sparked a rebound. The S&P 500 Index (^SPX) still fell 0.8%, with nine of the 11 sectors declining. But energy led, rising 2%, and it tops the sector derby at 44.5% year-to-date, observes Ed Yardeni, editor of Yardeni QuickTakes.
Communication services was the only other gainer, up 1.1%. Health care fell the most at 3.6%. Information technology was nearly flat at -0.2% and is up 23.2% YTD, with fundamentals that continue to improve.
(Editor’s Note: Ed will be speaking at the 2026 MoneyShow Masters Symposium Sarasota, scheduled for Nov. 30 – Dec. 2. Click HERE to register.)
We have recommended overweighting energy as a hedge against geopolitical risk. Brent crude oil fell below $90 a barrel in late August as diplomacy briefly eased tensions in the Persian Gulf. But last week, the US and Iran exchanged strikes, and Houthi attacks set Saudi oil facilities on fire. Brent futures rose to $104.61 on Friday.
The S&P 500 Energy index is at a record high. Leading the S&P 500 energy sector's 44.5% gain so far this year is the oil and gas refining and marketing industry, up 127.5%.
Still, the sector remains cheap and under-owned. It currently accounts for just 3.5% of the S&P 500 market capitalization and 4.7% of the index's forward earnings share. It's easy to overweight it. Earnings have driven the energy sector's rally. Forward earnings are up 57% YTD, while the forward P/E is down 7.9%.